Marriage changes a great many things, and money is quietly one of the largest of them. Two people who have spent their adult lives making financial decisions alone are suddenly making them together, very often without having sat down to discuss how.
Most couples work it out eventually, but the working out happens slowly, through small disagreements and unspoken assumptions rather than any real conversation. In Indian families, where money was rarely discussed openly at home, there is frequently no example to follow.
What follows is what genuinely changes when two incomes become one household, and the decisions far better made deliberately than stumbled into.
Deciding whether your money should be joint, separate, or somewhere in the middle
Almost every couple eventually lands on one of three arrangements, and none of them is the correct one. What matters is that the choice gets made on purpose rather than arrived at by drift.
A fully joint arrangement means everything you earn goes into one account and everything you spend comes out of it. It is simple and transparent, and it works beautifully for couples who genuinely think of their money as belonging to both of them. The difficulty arrives when one partner earns considerably more, because every purchase becomes visible and not every couple is comfortable living that way.
A fully separate arrangement means both incomes stay where they are and shared expenses get divided. This preserves an independence that matters enormously to people who have spent years answering to nobody about how they use their money. The trouble is that shared goals become harder to build towards, and somebody always ends up doing arithmetic at the end of the month.
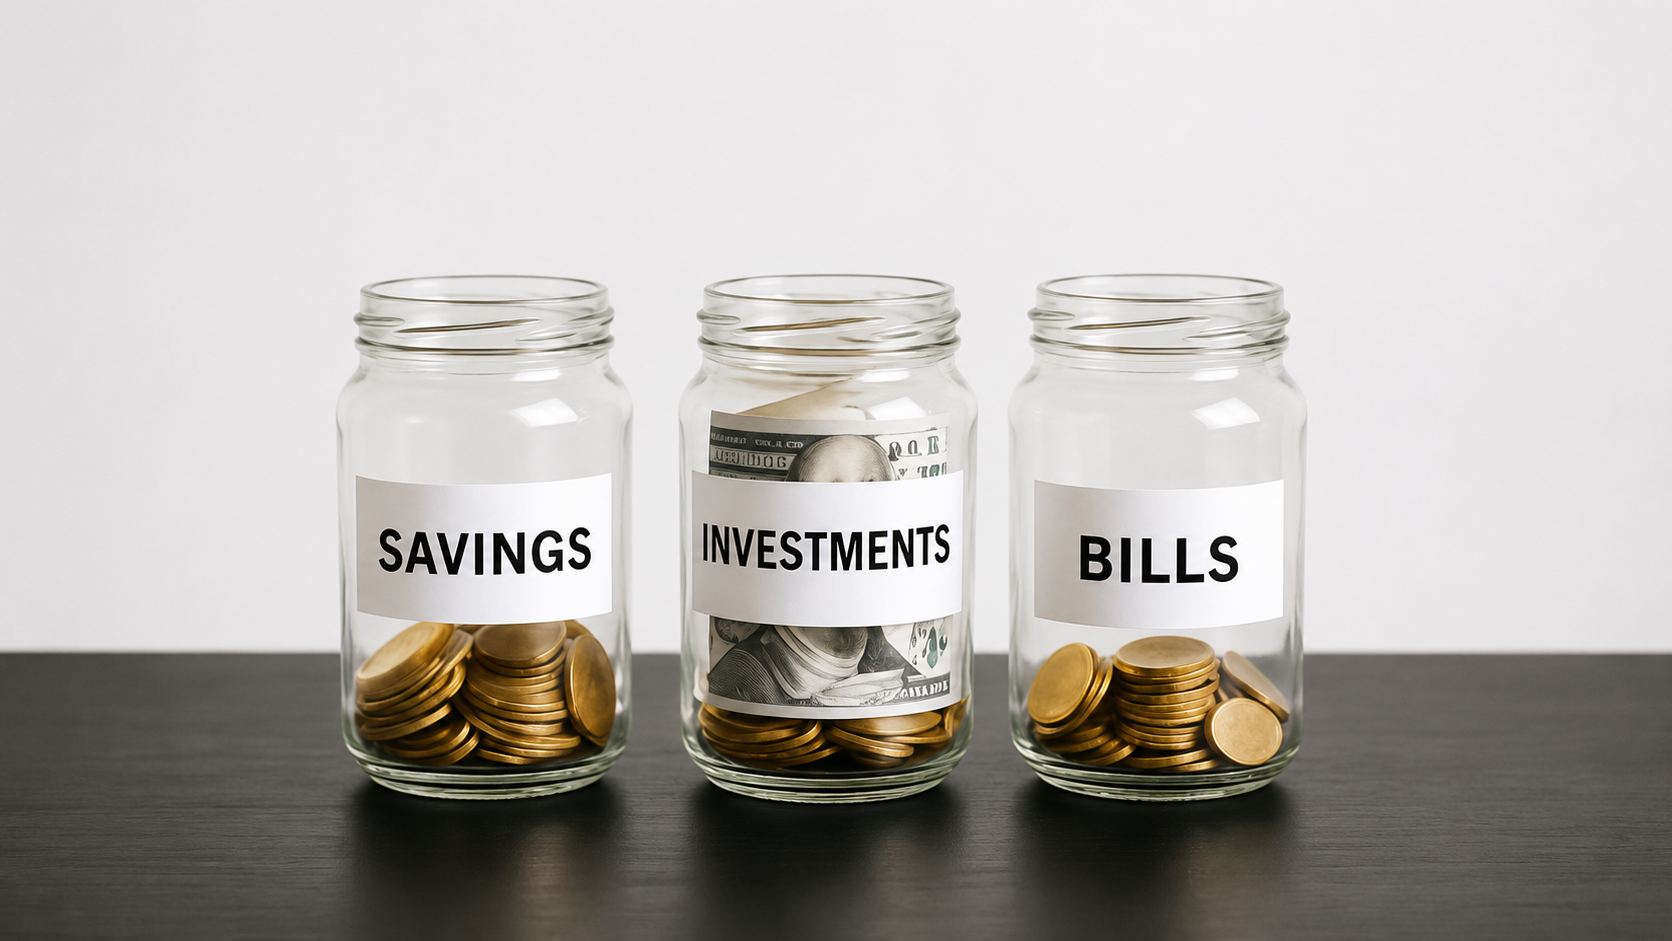
The hybrid is where most couples eventually settle. A joint account covers the shared parts of your life, meaning rent, bills, groceries and savings, while each of you keeps a personal account for everything else. Both contribute to the joint pot, and whatever remains is genuinely yours. It gives a couple a shared financial life without dissolving two individual ones, and for most people that balance is exactly right.
Splitting expenses by proportion rather than straight down the middle
When two incomes are meaningfully different, dividing shared expenses equally sounds fair and very rarely feels fair.
Consider a couple where one partner earns twice what the other does. An equal split leaves the lower earner with almost nothing at the end of the month while the higher earner still has room to move. Both paid the same figure, and only one of them actually felt it.
Proportional splitting resolves this. Each partner contributes in proportion to what they earn, so somebody bringing in sixty percent of the household income covers roughly sixty percent of the shared costs. Both of you end up with comparable freedom, which is almost certainly what fairness was supposed to mean.
It takes ten minutes to work out, and it quietly prevents years of resentment neither person would have known how to name.
Building the emergency fund before you build anything else
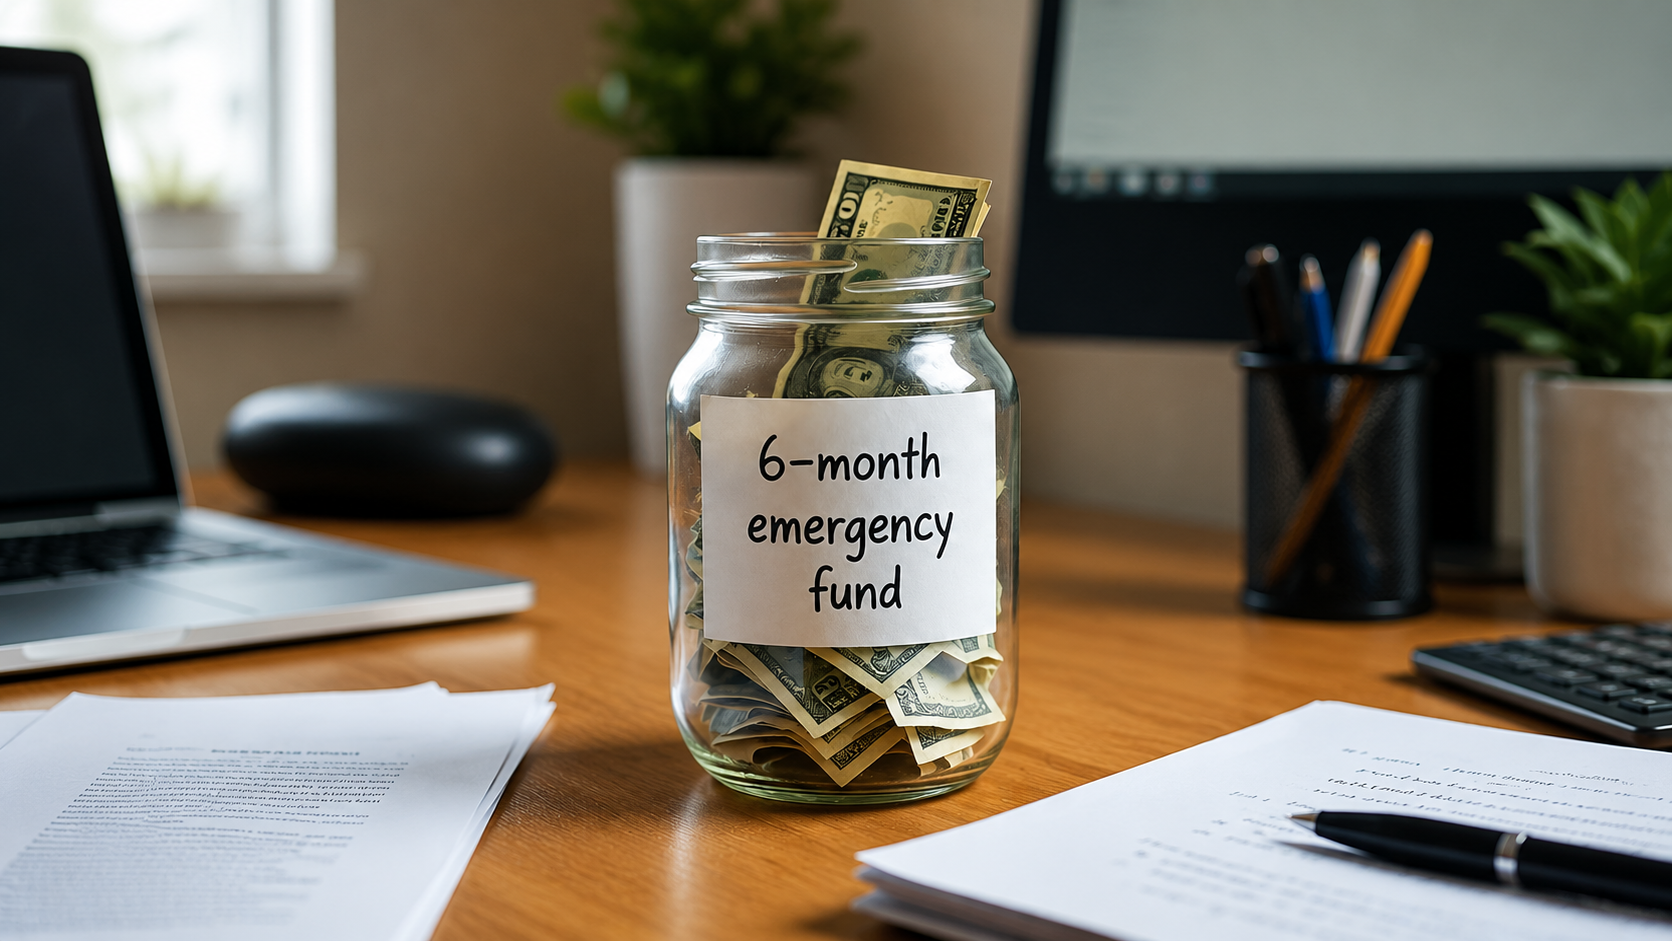
Before investing, before planning, before anything ambitious, most financial planners will tell you to build a cushion first. The usual guidance is three to six months of essential expenses, held somewhere you can actually reach quickly.
This is not interesting advice and nobody enjoys following it. But a married couple has considerably more that can go wrong. A job can disappear. A medical emergency can arrive without warning. A parent can fall seriously ill in a country you are not currently standing in. The difference between managing calmly and panicking is almost always whether money was set aside beforehand.
For couples living abroad the argument is stronger still, because a flight home at forty eight hours notice is expensive and very rarely optional.
Talking honestly about debt before it shapes your decisions
Very few couples enter a marriage free of debt, and almost nobody looks forward to raising it. Student loans, credit cards, a car not quite paid off, sometimes a loan taken years ago to help somebody in the family. None of these disappear at the wedding, and all of them shape what the two of you can do together.
The conversation is simpler than people fear. What do we each owe, what is it costing us monthly, and what are we going to do about it. There is no judgement required and rarely any need for blame. What matters is that both people work from the full picture, because it is impossible to plan around something you have never been told exists.
Whether those debts stay individual or become shared is each couple's decision. There is no universally correct answer, but there is a wrong one, and it is choosing not to discuss it at all.
Planning for parents, which most financial guides quietly ignore
Nearly every financial guide written in the West assumes a married couple's money belongs entirely to that couple. For many Indian families, that assumption does not survive contact with reality.
Sending money home to parents is not an inconvenience to be negotiated down. For an enormous number of couples it is a responsibility both partners accept willingly, and one neither would give up even if offered the option.
What it does need is planning rather than improvisation. How much goes home each month, to which family, and what happens when one set of parents suddenly needs a great deal more than the other. These questions are considerably more comfortable now than in the middle of a crisis.
Couples who talk about this early handle it gracefully for decades. Couples who discover it accidentally, six months in, very often do not.
Understanding where your wedding gifts fit into all of this
This is worth pausing on, because couples overlook it with remarkable consistency.
The money you receive at your wedding is, for most couples, the first significant sum you will ever hold together. Shagun from relatives, contributions from family, gifts from friends who wanted to help you begin well. It arrives all at once, at the exact moment you are starting your life together, and it is very easy to let it dissolve into the ordinary business of the following months.
How a couple handles that money tends to set the tone for everything afterwards. Those who sit down and decide together what it is actually for, whether a deposit, an emergency fund, or the honeymoon they have both quietly wanted, almost always find the next conversation about money easier than the first.
This is where digital Shagun makes a practical difference. Through Indivites, guests give from anywhere in the world through a designed gifting envelope, addressed to the couple or their parents exactly as the custom has always allowed, and every gift is recorded as it arrives. The couple begins married life knowing precisely what they received and from whom, which makes both the thank yous and the planning far more straightforward than a bag of unmarked envelopes ever allowed.
Coming back to the conversation as your life changes
Whatever the two of you decide in your first year will not stay right forever, and it is not supposed to.
Incomes change. Somebody gets promoted, or takes a pay cut to do work they actually care about, or stops working for a while. A child arrives. A parent needs far more support than anybody anticipated. You move countries. Every one of these quietly rewrites the arithmetic underneath the arrangement you originally agreed to.
The couples who handle money well over the long run are not the ones who found the perfect system at the beginning. They are the ones who go back and look at it again, honestly, once or twice a year.
The couples who struggle are rarely the ones who chose the wrong system. They are almost always the ones who never went back to check whether it was still working.
Frequently asked questions
Should married couples have a joint bank account? There is no single right answer, and happy couples use all three systems successfully. What matters is that the choice is made deliberately. The hybrid approach, with a joint account for shared expenses and individual accounts for personal spending, is where most couples settle.
How should couples split expenses when their incomes are different? Proportionally rather than equally is almost always fairer. If one partner earns sixty percent of the household income, they cover roughly sixty percent of shared expenses, leaving both people with comparable personal freedom.
How much should a married couple keep in an emergency fund? The usual guidance is three to six months of essential expenses, held somewhere accessible. Couples living abroad often prefer the higher end of that range, because the emergencies they face tend to involve flights.
Should we combine our debts after marriage? Every couple decides this for itself and both approaches work. What matters is that both partners understand the complete picture, including what is owed, what it costs monthly, and the plan for clearing it.
How do we plan for supporting parents in another country? Discuss it early and plan explicitly rather than handling it month by month. Agree how much goes home, to which family, and what happens when one side needs more than the other. Couples who settle this in advance rarely fall out over it later.
What should we do with the money we received at our wedding? Decide together and decide early, because this is often the first large sum a couple holds jointly. Many put it towards an emergency fund or a deposit. Digital Shagun through Indivites records every gift as it arrives, so you begin married life knowing exactly what you received and from whom.